Supreme Court Trade Exhibition Tax Decision
|
Getting your Trinity Audio player ready...
|
The Supreme Court of India has delivered an important ruling concerning the taxation of paid commercial exhibitions, holding that states can levy entertainment duty on exhibitions where visitors are admitted upon payment of an entry fee.
The decision concerns annual trade events organised by the Gem and Jewellery Export Promotion Council, including the India International Jewellery Show and IIJS Signature.
The council had challenged the levy of entertainment duty, arguing that these exhibitions were primarily designed for commercial purposes and business-to-business transactions rather than conventional entertainment.
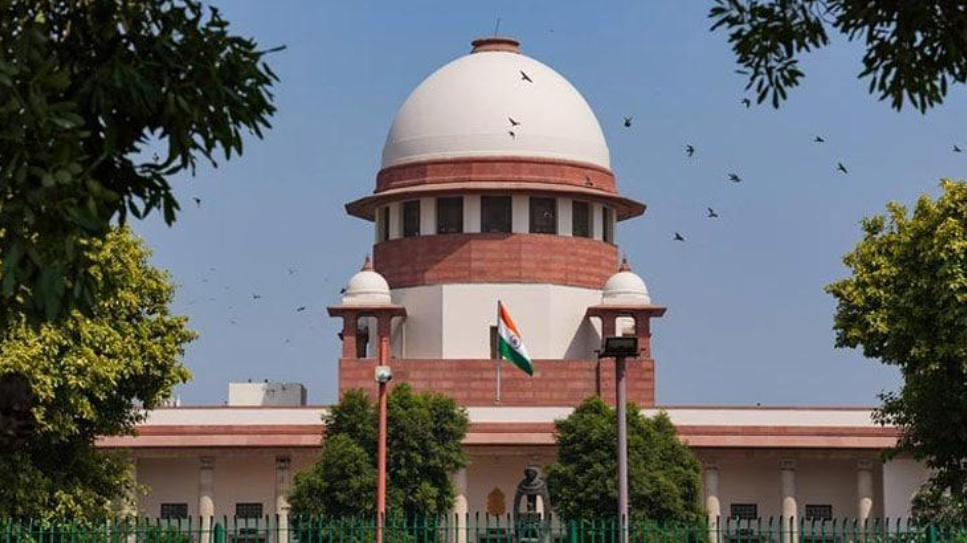
However, the Supreme Court rejected this argument and upheld the earlier decision of the Bombay High Court.
A bench comprising Justices S. V. Bhatti and N. V. Anjaria considered the provisions of the Bombay Entertainments Duty Act, 1923.
The court observed that the fact that an exhibition is organised for business purposes does not automatically remove it from the statutory definition of entertainment when visitors are required to pay for admission.
The ruling establishes an important legal interpretation concerning paid-entry exhibitions. Commercial objectives alone cannot necessarily exempt an event from applicable entertainment-duty provisions.
The decision could have implications for organisers of trade fairs, industry exhibitions, product showcases and commercial events in states where similar statutory provisions apply.
Organisers may need to examine their ticketing arrangements, entry charges and applicable state taxation requirements while planning future events.
However, the ruling should not be interpreted as imposing an automatic nationwide tax on every commercial exhibition. The actual tax liability will depend on the relevant state legislation and the specific circumstances of each event.
For the exhibition industry, the judgment highlights the importance of understanding the legal and financial responsibilities associated with paid admission.
The decision also reinforces the role of judicial interpretation in determining how state taxation laws apply to modern commercial activities.